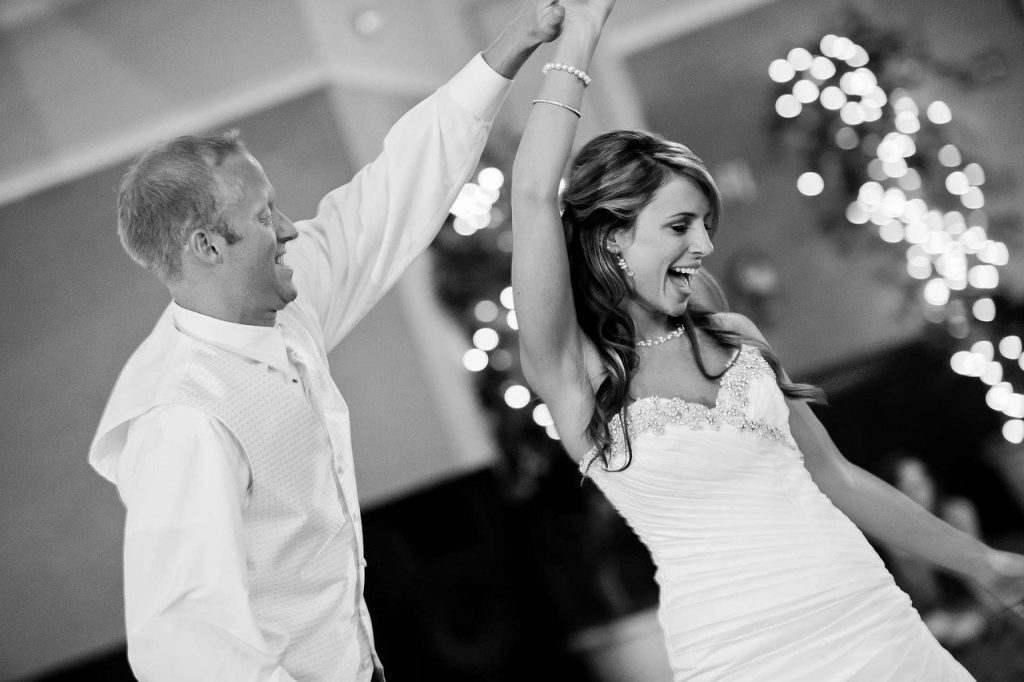
Wedding Dance

Surprise your guests Wedding dance choreography Calling all wedding couples, how would you like to dance your first dance to the music of your own choice have that special tune you both love, you know your song. Well let me choreograph your dance for you, not just a waltz or anything to fit in with the normal.

Your first dance is special. Your dance can be low key or as extravagant as you wish, if you desire you can also include your best man and bridemaids etc. All musical tastes catered for. Many years experience of teaching wedding couples, come and see sonia a trained choreographer in all music rhythmical styles.

Note for future bride grooms, fellows don’t panic its great fun, we havent had a failure yet! .

Anniversary, Engagement and Special Occassion Dances, Themed Events

Have you got a special anniversary, engagement or another special occasion in your life, suprise your family and friends, with a dance routine that will be remembered for a lifetime, easy step by step instruction, friendly atmosphere.

We cater for singles, couples, groups, your chosen music can be anything from comedy, Hip Hop, romantic, dirty dancing, ballroom, latin, salsa, rock n roll, lindy hop, jive, themed events a speciality, etc. Anything you wish for your party suprise, we have done it all romantic, low key, spectacular even bizzare, give Sonia a call.

Related Post

Hur man erhåller ritningar för bygglovHur man erhåller ritningar för bygglov

Inledning

Att få ett byggtillstånd behöver du lämna in

bygglovsritningar

till kommunen. Dessa ritningar är essentiella för att kommunen ska kunna bedöma ditt byggprojekt och säkerställa att det uppfyller alla byggnormer och krav.

Vad är bygglovsritningar?

En byggnadsritning består av ofta flera olika typer ritningar, såsom planritningar, fasadritningar och sektioner. Dessa visar detaljer om husets design, struktur och position på tomten.

Professionell hjälp med bygglovsritningar

För att erhålla stöd med dina bygglovsritningar kan du ta hjälp av en byggnadsarkitekt eller en konstruktör. Professionella experter har den rätta kunskapen och färdigheterna för att skapa exakta och detaljerade ritningar som följer tillståndsprocessens krav och standarder.

Varför anlita en professionell?

Det finns flertalet fördelar med att engagera en yrkesmässig att ta fram bygglovsritningar. En arkitekt har förmågan att assistera er att designa ett byggprojekt som både är praktiskt och visuellt attraktivt. Vidare besitter de kännedom om de lokala byggnormerna och kan garantera att ditt projekt är i enlighet med dem.

Vikten av tydlig kommunikation

När du väljer att hyra in en arkitekt, är det viktigt att förmedla dina visioner och önskemål klart och tydligt. Med en öppen och ärlig kommunikation har specialisten skapa en plan som motsvarar dina förväntningar och behov.

Att navigera bygglovsprocessen

Förutom assistans med själva ritningarna kan en fackman också hjälpa er med att hantera bygglovsprocessen. Denna inkluderar att fylla i ansökningsblanketter, insända nödvändiga dokument och att följa upp förfrågningens status.

Sammanfattning

Genom att ha professionell assistans kan göra hela din förfarandet smidigare och mer effektiv. Det kan hjälpa till att minska sannolikheten för misstag och problem som kan leda till förseningar eller nekande på ditt tillstånd.

Sammanfattningsvis, om du har för avsikt att bygga eller bygga om ett hus, är det anlita en professionell för assistans av byggnadsritningar. Detta kan garantera att ditt initiativ är i linje med samtliga bestämmelser och standarder, vilket därmed leder till en smidigare och mer framgångsrik tillståndsprocess.

Instant Cash Advance: The Best Tips to Get Instant Cash Advance LoansInstant Cash Advance: The Best Tips to Get Instant Cash Advance Loans

Find out everything you need to know about instant cash advance loans using IAC loans!

It is well known that life is unpredictable.

If you need cash quickly and are in financial trouble, an instant cash advance could be your solution.

But how do they get one?

IAC loans offers 5 suggestions to help you to locate a cash advance.

At any point in this article if you think you want to get an instant cash advance online then feel free to go to our website and get your debit card cash advance near me today!

1. What is an instant cash Advance and How Does It Work?

A cash loan that is instant is a short-term loan which can be utilized in any way.

Instant cash advances are typically utilized in times of need, like when your washing machine breaks down.

They may also be used to cover small expenses or to pay bills.

Some instant cash advances let you borrow up to $1,000, which may appear to be an amount of money, but it will need to be repaid within a year, at a time.

2. 2. How to Apply for an instant cash advance

The process of applying for an instant cash advance is going to look a little different than the regular loan process.

The lender will review your application. This lender will request information such as your monthly income, credit score and if you’ve ever borrowed the cash advance in an instant.

The person who is lending you the cash advance may also ask why you want the advance and what you plan to accomplish with it.

Once your application is approved they’ll inform the applicant whether they’ve given you money.

3. The advantages of instant cash advances Loans

Instant cash advance loans are a good alternative because you can get the cash immediately and return to your normal routine.

It’s temporary but fast.

It is possible to apply for an instant cash advance onlineand once you’ve found a lender you’ll be able to have the cash transfered directly to your bank account within 24 hours.

4. What is the process by which Instant Cash Advances function?

Instant cash advances function by using the person’s income as collateral.

The lender also considers how much the worker is earning per month, their credit score and whether they’ve ever taken out an instant cash loan.

They’ll are also interested in knowing why you need the instant cash advance and if you’re going to make use of it for something specifically.

Once your application is approved, they’ll either give you the money or inform you that your application has been rejected.

If they haven’t yet paid you yet, they’ll let it know. Thenthe funds will be transferred automatically to your chosen bank or bank account. Most often, it happens within 24 hours.

5. You may be interested in looking at cash advances that are instant

It is possible to look into instant cash advances if you need to quickly pay for unexpected expenses.

Online applications for instant cash advances are possible. After they find a lender, accept their request, money will be sent directly to their bank account within 24 hours.

Important to remember that this is only temporary, and the money has to be returned within a year.

The lender will decide the length of time you must be patient, but it should take between 6 months and a year.

This works because once you have received your cash, they begin charging you interest. You should pay the money back within this time frame.

The cash advance loan is often misunderstood. Howeverthey are an effective financial tool that will help you reach your objectives.

Cash advances are a great way to get your financial situation back on track when you make them use wisely and with a good plan.

The five tips we’ve provided today should hopefully make it easier to find the perfect loan provider for your needs.

If an instant cash advance payday loan seems like the right choice for you then come visit us at instantadvancecash.com

We have many years of experience in helping people just like yourself get money quickly when they need them most so now might be the perfect time to require one as well.

You can get started today with your cash loanapplication by visiting our website!

https://www.instantadvancecash.com/

What’s an IUL? Decoding Indexed Universal LifeWhat’s an IUL? Decoding Indexed Universal Life

Ever found yourself at a crossroads, trying to decipher the code of financial security and prosperity? Yes, we’ve all been there. Now, imagine stumbling upon a roadmap that not only promises to guide you but also introduces an intriguing concept: what’s an iul. Sounds like something out of a financier’s diary, Right?

This isn’t your everyday money talk. Far from it. Indexed Universal Life (IUL) insurance flirts with the boundary between daring investment and cautious savings plan. It’s Where the thrill of stock market indexes meets the steadfastness of life insurance.

The allure? A chance at higher returns without lying awake fearing market downturns. But here’s the kicker – those potential gains have limits. Yes, caps on how much you can earn might just be IUL’s way of saying “let’s keep this interesting.” And let’s not forget; it demands more than pocket change for its premium costs compared to simpler life policies.

Understanding Indexed Universal Life (IUL) Insurance

What Is an IUL Account?

Imagine a world where your life insurance does more than just offer peace of mind for the unexpected. Enter: indexed universal life (IUL) insurance. It’s not just any policy; it’s a savvy blend of protection and potential growth, wrapped up in one neat package.

How Does an IUL Account Work?

IUL policies are like the Swiss Army knife of the insurance world. Offering adjustable payments, these plans allow you to modify your contribution amounts within specified boundaries. But here’s where it gets interesting: part of your premium goes into accounts that can be tied to market indexes like the S&P 500 or Nasdaq-100. Think smart savings with a twist – while there’s a safety net ensuring you won’t lose cash when markets dip, there’s also a cap on how high your returns can go. And yes, this means sometimes dancing close to those caps when markets soar.

Is an IUL Account a Good Investment?

This is where opinions diverge faster than forks in fairy tales. Some say IULs shine brighter than traditional universal life policies, thanks to their earning potential tied to market performance—without directly exposing your hard-earned money to market risk. Others caution about capped gains and costs that might nibble away at what could have been yours outright had risks been taken elsewhere.

  • If retirement planning feels akin to navigating through fog without lights, adding an IUL could turn on some headlights.
  • If already maxing out other retirement avenues or seeking tax advantages offered by life insurance products.
  • If keen on leaving behind something substantial for loved ones while enjoying some financial perks along the way.

The truth? Whether an IUL account beams as brightly as Sirius in our night sky comes down mostly to personal circumstances and preferences – but getting acquainted with all its ins-and-outs is key before diving deep into its waters.

Key Takeaway: 


Think of an IUL as a smart combo of life insurance and potential market growth, with flexible premiums and safety nets. It’s perfect for those navigating retirement planning or wanting to leave something behind, but it’s essential to weigh its benefits against capped gains and costs.

The Benefits and Downsides of IUL Insurance

Pros: Indexed Universal Life Insurance

First up, the positives – who doesn’t love kicking things off on a bright note? Indexed Universal Life (IUL) insurance isn’t just another life insurance policy. It’s like the Swiss Army knife in your financial toolkit. Why?

  • Potential for higher returns: Unlike its cousin, traditional universal life policies, an IUL can give you a leg up with returns tied to market indexes. But don’t worry; there’s a safety net ensuring you won’t dive into negative territory when markets falter.
  • Tax-deferred growth on cash value: The IRS isn’t getting their hands on this till much later. That means more money compounding over time.
  • A sidekick for retirement planning: Imagine having a bucket of money that grows tax-free which you can dip into during retirement without triggering taxes or penalties? Yep, an IUL has got your back.
  • Lifelong coverage plus flexibility: Need to adjust how much you’re paying or what your beneficiaries get after you’ve moonwalked off this mortal coil? With an IUL, it’s no biggie.

Cons: Indexed Universal Life Insurance

No sugarcoating here – while IULs have their perks, they come with caveats too.

  • Capped gains mean limited fun: We love those years when the stock market is throwing a party because everyone’s portfolio gets fat… unless yours is capped because of your IUL policy terms.
  • You might need a PhD in patience and persistence: I’m kidding about the degree part but not about needing heaps of patience. Managing these policies takes work, keeping track so it doesn’t lapse due to underpayment.
  • Those pesky premium costs: Let’s be real—Quality comes at a price. While term life lets folks sleep easy knowing they’ve spent less, IUL asks for more upfront. And over time. That dough could potentially do better elsewhere, given half a chance.

There you go. The rundown on pros and cons. When considering if IUL is the right fit for you, weighing both sides is an essential step. So, make sure to grab a notepad and jot down how these factors align with your financial goals.

Key Takeaway: 


Think of IUL insurance as your financial Swiss Army knife: offering potential for higher returns, tax perks, and retirement help but watch out for caps on gains, the need for patience in management, and those premium costs.

Comparing IUL to Other Life Insurance Products

Indexed universal life insurance vs. term life insurance

Let’s kick things off with a classic face-off: IUL versus term life. The biggest difference? The crux of the matter lies in their longevity and the presence, or absence, of a monetary worth attached. Term life insurance is like renting an apartment – you’re covered for a set period, say 20 years, but when the lease is up, that’s it. No equity or cash value to show for it.

In contrast, indexed universal life (IUL) offers something more permanent. Think of it as buying a home – not only do you have lifelong coverage but there’s also potential to build cash value over time based on market indexes.

Indexed universal life insurance vs. whole life insurance

Moving onto the next contender: whole life insurance. This one’s got longevity in its corner too; providing lifetime coverage just like IULs do.

The main event here though? The way they handle your money. Whole-life policies are the steady Eddies offering guaranteed returns on your cash value component – slow and stable wins the race kind of vibe.

But if you’re feeling adventurous, an IUL throws in some spice by tying your earnings potential to stock market indexes without direct investment risk. It’s like having both safety nets and trampolines underfoot.

Indexed universal life insurance vs. variable life insurance

Last up we’ve got variable life insurance going head-to-head with our star player: IULs.

This showdown is all about control versus flexibility. Variable policies hand over the reins letting policyholders directly invest their cash values into stocks or bonds—big rewards if you know what you’re doing. On the flip side, IULs keep things a bit more reined in. Your cash value grows based on selected market indexes with caps and floors to protect you from wild market swings. So what’s our takeaway here? When picking between term life, whole life or variable policies versus an indexed universal one, it all boils down to how much risk you’re willing to take on for potential rewards and whether longevity of coverage is key for you.